Retail payment solutions in Dubai fail in the queue, not in a pitch deck. If Apple Pay is missing, the terminal is slow, or the online order cannot be refunded from the same system as the till, you do not have retail payment solutions. You have a drawer of devices.
This page is for in-store and omnichannel: POS terminals, contactless, wallets, and how they join payment solutions UAE and online payment gateways UAE without splitting the customer. Swasthe’s payment partner is uTap (etisalat by e&, powered by Mswipe), so the terminal and the website gateway can be one merchant setup instead of two vendors.
What retail payment solutions must cover
- Contactless cards and phones (Apple Pay, Google Pay) as the default, not a “phase two.”
- A terminal that still takes a card if Wi-Fi drops for two minutes.
- The same merchant / customer identity as ecommerce pickup.
- Refunds and voids that a supervisor can do without calling IT in another emirate.
- End-of-day totals that match the POS, not a second spreadsheet from the acquirer portal.
Network International and bank-branded terminals are common in Dubai malls. Independent specialty stores often add a gateway terminal or a softPOS. Swasthe partners with uTap for that omnichannel path: till, Apple Pay, and the same online payment gateway for pickup orders. The brand on the plastic still matters less than whether the sale posts to inventory and loyalty in one tap.
Dubai floor realities
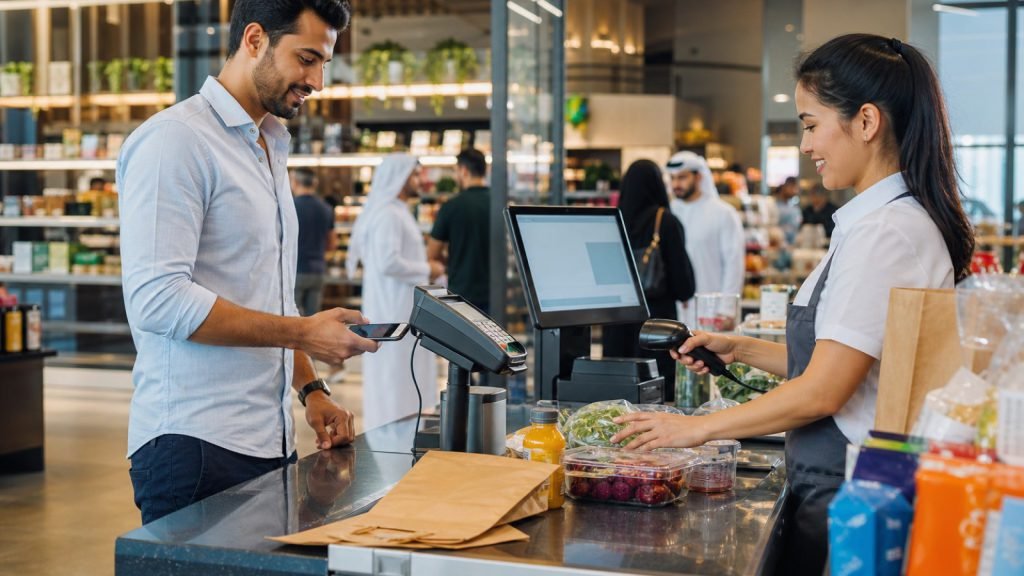
Peak hours in Dubai malls punish extra screens. Retail payment solutions Dubai teams keep are: one prompt, one receipt, loyalty optional in the same flow. If loyalty is a second app after payment, staff skip it. That is why a loyalty program management system Dubai has to live inside the payment step, not after it.
Tourists bring foreign cards. Have a fallback. Locals tap phones. If your device is chip-and-pin only, you trained people to leave.
Connecting store payments to online
Click-and-collect dies when the website gateway and the store terminal cannot see each other. Retail payment solutions should share:
- Order ID and SKU
- Paid / unpaid / refunded status
- The customer phone number used for WhatsApp updates
ElintOm is the ops layer for that truth. Swasthe’s Retail Growth work then points ads at a path that can actually take money.
Cost view owners should demand
Do not compare only MDR. Add terminal rental, PCI scope, chargeback time, and staff minutes per exception. Cheap retail payment solutions UAE quotes that need a manager for every refund are expensive.
Rollout plan for one store, then a second
- Shadow the current till for two busy hours. List every payment type that appeared.
- Turn on wallets if they are off.
- Map refunds and no-receipt customers.
- Tie the terminal to POS stock and, if you run points, to loyalty.
- Only then copy the setup to store two.
FAQ: retail payment solutions
What are the best retail payment solutions for a Dubai specialty store?
With Swasthe, uTap is the payment partner for terminal + Apple Pay + online payment gateway, wired to POS. A bank or Network terminal can stay if it already reconciles. Do not add a third random website app—see the UAE gateway guide.
Do I need a separate system for WhatsApp invoices?
Prefer payment links from the same gateway so settlement stays one file.
Where do pharmacies differ?
OTC retail payments look like any specialty till. Insurance is separate. See pharmacy software companies Sharjah.
If the queue, the website, and WhatsApp all take money differently, book a free audit. We will say which payment leak to fix before you buy another terminal.
What are the latest Central Bank of the UAE regulations regarding digital retail payments?
The Central Bank enforces strict Retail Payment Services and Card Schemes regulations, requiring licensed acquiring, end-to-end data encryption, and consumer protection standards for all merchant transactions.
How does integrating physical card terminals with your retail POS eliminate cashier calculation errors?
Integration transmits the exact bill total directly from the POS to the payment terminal screen. The cashier does not re-type numbers, preventing undercharging or billing mistakes.
What is Jaywan, and how will the UAE domestic card scheme affect retail payment fees?
Jaywan is the UAE’s national domestic payment card scheme. It aims to lower merchant transaction processing costs, enhance domestic payment security, and reduce reliance on international card networks.
How do multi-store retailers manage terminal fleet management across multiple Dubai shopping malls?
Retailers use centralized terminal management software provided by partners like uTap, monitoring terminal uptime, software updates, and daily transaction volumes across all mall branches remotely.
What should a retailer do when a customer claims their card was debited but the POS shows payment failure?
Check the EDC terminal receipt. If the terminal prints a ‘Declined’ slip, the bank charge is usually a temporary pre-authorization hold that reverses automatically within 24 to 48 hours.
Can retail payment solutions in Dubai accept international digital wallets like Alipay and WeChat Pay?
Yes, smart terminals can be configured with dynamic QR code scanners to accept Alipay and WeChat Pay, capturing high-ticket retail purchases from visiting Chinese tourists.
How does contactless payment speed impact checkout queue abandonment during weekend mall peaks?
Fast contactless card and wallet taps keep queues moving quickly. Reducing queue wait times prevents shoppers from abandoning baskets during peak Friday and Saturday mall shopping hours.
What are the chargeback dispute timeframes for credit card transactions in the UAE?
Acquiring banks typically give merchants 7 to 14 days to provide signed receipts, delivery notes, or CCTV proof of collection to dispute and overturn illegitimate customer chargebacks.
How does uTap’s EDC terminal integration simplify daily cashier shift handovers and Z-reports?
At shift end, the POS automatically reconciles till transactions against the terminal’s batch totals, highlighting any cash or card discrepancies on the cashier’s printed closing report.
What recurring rental or monthly maintenance fees apply to retail card swipe machines in Dubai?
Fees typically include a monthly terminal rental fee (or one-time hardware purchase), SIM connectivity charges, and standard merchant discount rate (MDR) percentages per transaction.
How can specialty retailers accept remote payments safely for phone and WhatsApp orders?
Generate secure payment links via your merchant portal or POS and send them to the customer via WhatsApp. Customers complete payment via Apple Pay or credit card on a verified payment page.
Terminal placement and queue physics
Retail payment solutions fail when the pin pad sits behind a perfume tester the customer cannot reach. Dubai malls run tight counters. Mount the contactless zone where the bagging hand already is. If staff must rotate the terminal 180 degrees, you added two seconds to every basket. Multiply that by Saturday.
Watch a real peak. Retail payment solutions that looked elegant in a vendor showroom often hide the NFC sweet spot under a poster. Move the poster.
Offline mode and “the line is down”
Malls lose connectivity. Retail payment solutions should store-and-forward or have a documented voice-auth fallback your acquirer accepts. If the only plan is “use the other store’s phone hotspot,” write that down and test it. Customers will not wait for a reboot lecture.
Tourist cards and scheme mix
Dubai traffic is not only UAE debit. Retail payment solutions that disable a scheme to “save MDR” will decline visitors who were ready to buy. Track decline codes weekly. If foreign cards fail, call the acquirer before you blame ads. Pair this with the payment solutions UAE stack so online pickup uses the same merchant story.
Cash, wallets, and the drawer policy
Cash still appears. Retail payment solutions include the boring SOP: who opens the drawer, when to drop large notes, how a wallet refund differs from cash. If Apple Pay refunds go to a card the tourist no longer has, staff need a script. Write it. Mystery refunds destroy the Monday cash-up.
Scheme and wallet rules change; your acquirer and Apple Pay merchant information are the source of truth for wallet behaviour, not a WhatsApp rumour in the staff group.
The Saturday test Swasthe uses
We time enrol-plus-pay on a real SKU, then a refund, then a WhatsApp payment link for a pickup order. With Swasthe, that link and till usually run on uTap, our payment partner. Retail payment solutions that pass that test can support ads. Those that fail get a Build week, not a bigger media budget. That is the whole engine: till truth first, traffic second.